
Most businesses discover a payroll compliance problem the same way, a notice arrives, interest has already accrued, and nobody can explain how the deadline was missed.
It rarely happens through negligence. Payroll in India sits at the intersection of at least five separate laws, each with its own registration thresholds, filing dates, and penalty structure. A company with twenty employees is already juggling provident fund, employees’ state insurance, tax deducted at source, professional tax, and state-specific labour welfare contributions. Miss one, and the cost is not just the penalty, it is the interest, the officer visit, and the time your finance team loses resolving it.
This guide lays out what Indian businesses are required to file, when each deadline falls, and where companies most often slip.
Why Payroll Compliance Fails More Often Than You Think
Payroll looks like a monthly administrative task. It is actually a monthly legal obligation with several moving parts that change independently of each other.
Contribution rates get revised. Wage ceilings are amended. State professional tax slabs differ from one state to the next, so a company with offices in Delhi and Karnataka is managing two entirely separate schedules. Employee headcount crosses a threshold mid-year and triggers a registration requirement nobody was watching for.
The underlying problem is that payroll compliance is treated as a finance function when it is really a regulatory one. That mismatch is exactly why many organisations move the entire function to a specialist, our payroll outsourcing services in Delhi exist for precisely this reason.
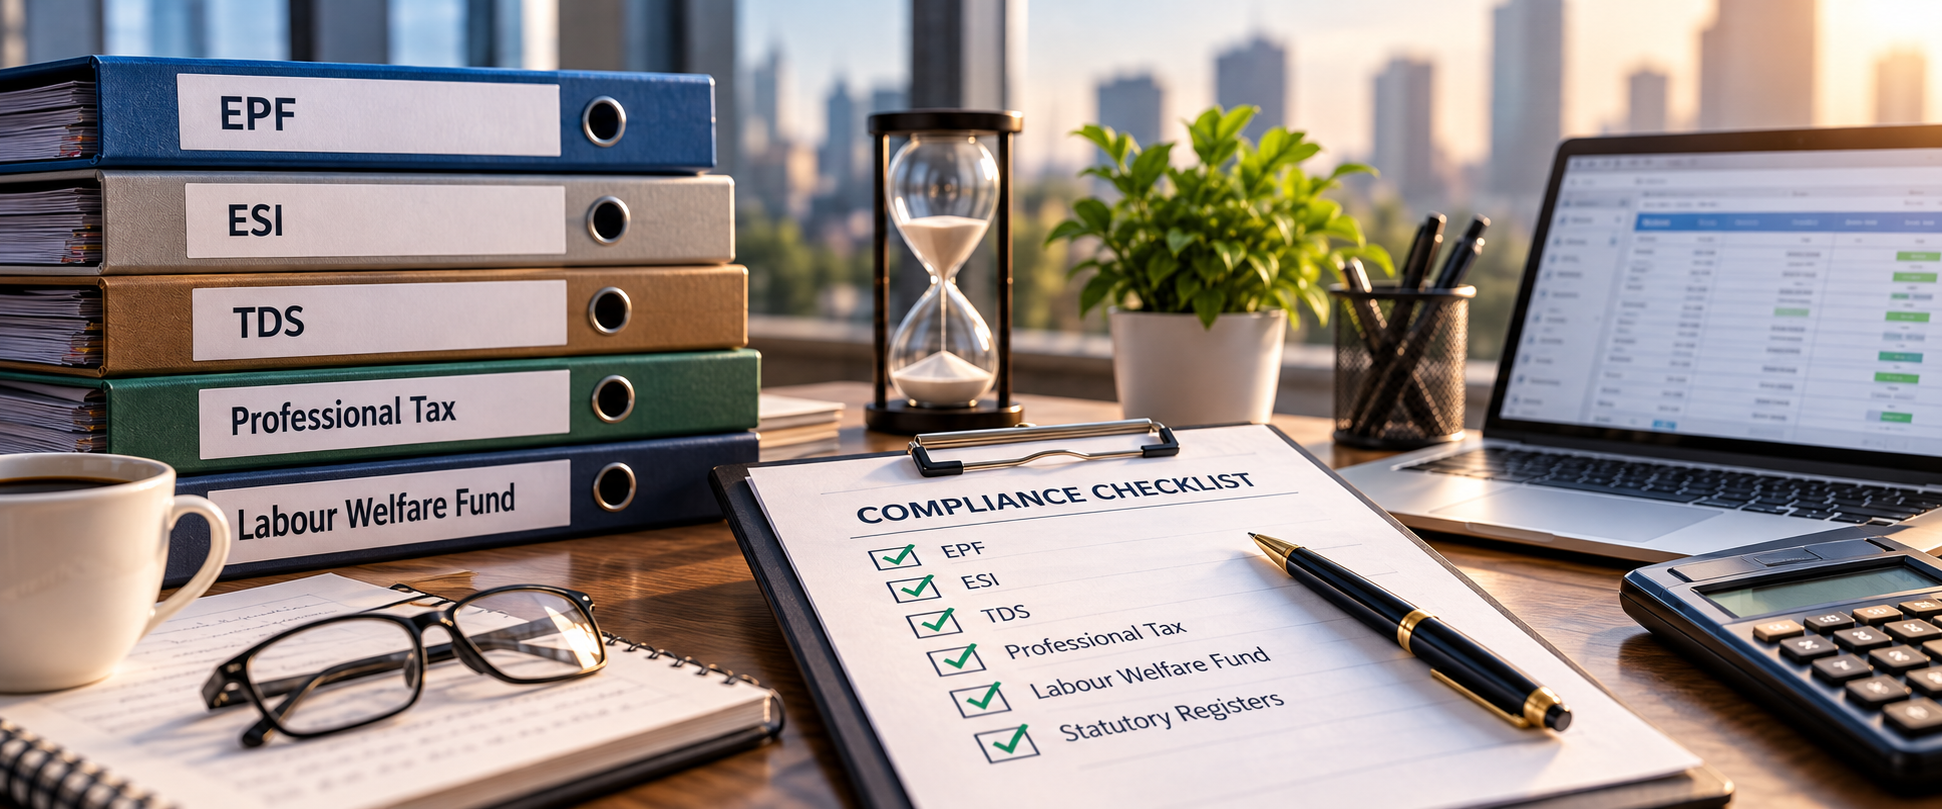
The Core Payroll Compliance Checklist
1. Provident Fund (EPF)
Applies to: Establishments with 20 or more employees. Voluntary registration is available below that threshold.
What is required:
Register the establishment and obtain an EPF code. Deduct the employee contribution and add the employer contribution each month. File the monthly ECR (Electronic Challan cum Return) and deposit the challan.
Deadline: 15th of the following month.
Where businesses slip: Treating contract workers and consultants inconsistently. Misclassifying an employee as a consultant to avoid the contribution is a common shortcut that creates significant liability during an inspection.
2. Employees’ State Insurance (ESI)
Applies to: Establishments with 10 or more employees (20 in some states), covering employees earning up to the prescribed wage ceiling.
What is required:
Obtain an ESI code for the establishment. Register each eligible employee and generate their insurance number. Deduct and deposit monthly contributions.
Deadline: 15th of the following month. Half-yearly returns are filed in May and November.
Where businesses slip: Failing to re-assess coverage when an employee’s wages cross or fall below the ceiling mid-year. Coverage is determined at the start of each contribution period, not continuously.
3. Tax Deducted at Source (TDS) on Salaries
Applies to: Every employer paying taxable salary.
What is required:
Calculate TDS based on each employee’s declared investments and chosen tax regime. Deposit the deducted amount monthly. File quarterly TDS returns in Form 24Q. Issue Form 16 to employees annually.
Deadlines: TDS deposit by the 7th of the following month. Quarterly returns by the 31st of the month following each quarter, with the Q4 return due 31st May. Form 16 issued by 15th June.
Where businesses slip: Accepting investment declarations in April and never collecting proof in January. When employees fail to produce documentation, the shortfall becomes the employer’s problem in the fourth quarter.
4. Professional Tax
Applies to: Businesses operating in states that levy it, including Maharashtra, Karnataka, West Bengal, Tamil Nadu, Gujarat and others. Delhi does not currently levy professional tax.
What is required:
Registration certificate for the employer and enrolment certificate for employees. Deduction at state-specified slab rates and periodic filing.
Deadline: Varies by state, monthly in some, annually in others.
Where businesses slip: Multi-state operations. A company headquartered in Delhi with a sales team in Mumbai still has a Maharashtra professional tax obligation, and it is routinely overlooked.
5. Labour Welfare Fund
Applies to: Establishments in states that operate a welfare fund, including Maharashtra, Karnataka, Haryana and others.
What is required:
Employee and employer contributions at state-specified rates, deposited on the state’s schedule, typically half-yearly or annually.
6. Statutory Registers and Records
Beyond the filings, several registers must be maintained and produced on demand during an inspection: the register of wages, register of employees, attendance records, leave register, and records under the Payment of Bonus Act and Payment of Gratuity Act where applicable.
These are the records that get requested first during any labour inspection, and incomplete registers often cause more difficulty than a late filing would have.
The Annual Obligations Businesses Forget
Monthly filings get attention because they recur. Annual obligations get missed because they arrive once and there is no routine built around them.
Bonus payment under the Payment of Bonus Act must be paid within eight months of the close of the accounting year, with Form D filed accordingly.
Gratuity provisioning applies to employees completing five years of continuous service, and the liability should be recognised in your books rather than discovered at the point of exit.
Annual returns under applicable Shops and Establishments Acts vary by state and are commonly overlooked by businesses that registered years ago and never revisited the requirement.
Form 16 issuance to every employee from whom TDS was deducted, including those who left during the year.
Building Controls Instead of Relying on Memory
A checklist only works if something enforces it. The organisations that stay compliant do not have better memories, they have better controls.
That means documented approval workflows before disbursement, segregation between the person who prepares payroll and the person who approves it, a reconciliation between the payroll register and the bank disbursement every month, and an audit trail for every change to employee master data.
This is the thinking behind internal controls in payroll systems, and it is also why many businesses move to paperless payroll processing, a digital trail is far easier to audit than a folder of signed printouts.
For organisations that want an independent assessment of where the gaps actually are, a regulatory compliance audit will identify exposure before a regulator does.
When Outsourcing Makes More Sense Than Hiring
There is a point at which building payroll capability in-house stops being economical.
A compliance-capable payroll resource needs to track amendments across multiple statutes, manage state-wise variation, and stay current with filing portals that change without notice. For a company with under two hundred employees, that is rarely a full role, but the knowledge requirement is the same as it would be for a company with two thousand.
Outsourcing resolves the mismatch. You get the specialist knowledge without carrying the headcount, and the liability for accuracy sits with a provider whose entire business depends on getting it right.
ACATL provides payroll outsourcing for corporate organisations covering the complete cycle, processing, statutory challans, return filing, and ESI, EPF and EPT code management. For businesses rethinking their pay structures alongside the move, our compensation consulting work addresses structure and tax efficiency together.
Many clients combine payroll with accounting outsourcing so that payroll entries flow directly into the books without a reconciliation step, and with assurance and attestation where statutory certification is required.
A Note for Early-Stage Companies
Newly incorporated companies face the same obligations as established ones, usually without anyone internally responsible for tracking them.
The first year typically requires statutory auditor appointment within thirty days of incorporation, board meetings with maintained registers, GST registration where applicable, and PF and ESI registration triggered the moment headcount crosses the threshold.
Founders also benefit from addressing documentation early founders’ agreements, employment contracts and vendor agreements. Our legal assistance team handles this alongside the compliance work, and protecting the business identity through trademark registration is considerably cheaper at this stage than resolving a dispute later.
Where to Start
If you are unsure where your organisation currently stands, start with three questions. Are all applicable registrations in place for every state you operate in? Has every monthly filing for the current financial year been deposited on time? Are your statutory registers complete and available if an inspector asked tomorrow?
If any answer is uncertain, that is the gap worth closing first.
ACATL has supported businesses across Delhi NCR for over twenty-three years with payroll, compliance and corporate services. Get in touch for a review of your current payroll compliance position we will tell you exactly what needs attention and in what order.