Payroll Compliance Checklist for Indian Businesses: What You Must File and When

Most businesses discover a payroll compliance problem the same way, a notice arrives, interest has already accrued, and nobody can explain how the deadline was missed.

It rarely happens through negligence. Payroll in India sits at the intersection of at least five separate laws, each with its own registration thresholds, filing dates, and penalty structure. A company with twenty employees is already juggling provident fund, employees’ state insurance, tax deducted at source, professional tax, and state-specific labour welfare contributions. Miss one, and the cost is not just the penalty, it is the interest, the officer visit, and the time your finance team loses resolving it.

This guide lays out what Indian businesses are required to file, when each deadline falls, and where companies most often slip.

Why Payroll Compliance Fails More Often Than You Think

Payroll looks like a monthly administrative task. It is actually a monthly legal obligation with several moving parts that change independently of each other.

Contribution rates get revised. Wage ceilings are amended. State professional tax slabs differ from one state to the next, so a company with offices in Delhi and Karnataka is managing two entirely separate schedules. Employee headcount crosses a threshold mid-year and triggers a registration requirement nobody was watching for.

The underlying problem is that payroll compliance is treated as a finance function when it is really a regulatory one. That mismatch is exactly why many organisations move the entire function to a specialist, our payroll outsourcing services in Delhi exist for precisely this reason.

The Core Payroll Compliance Checklist

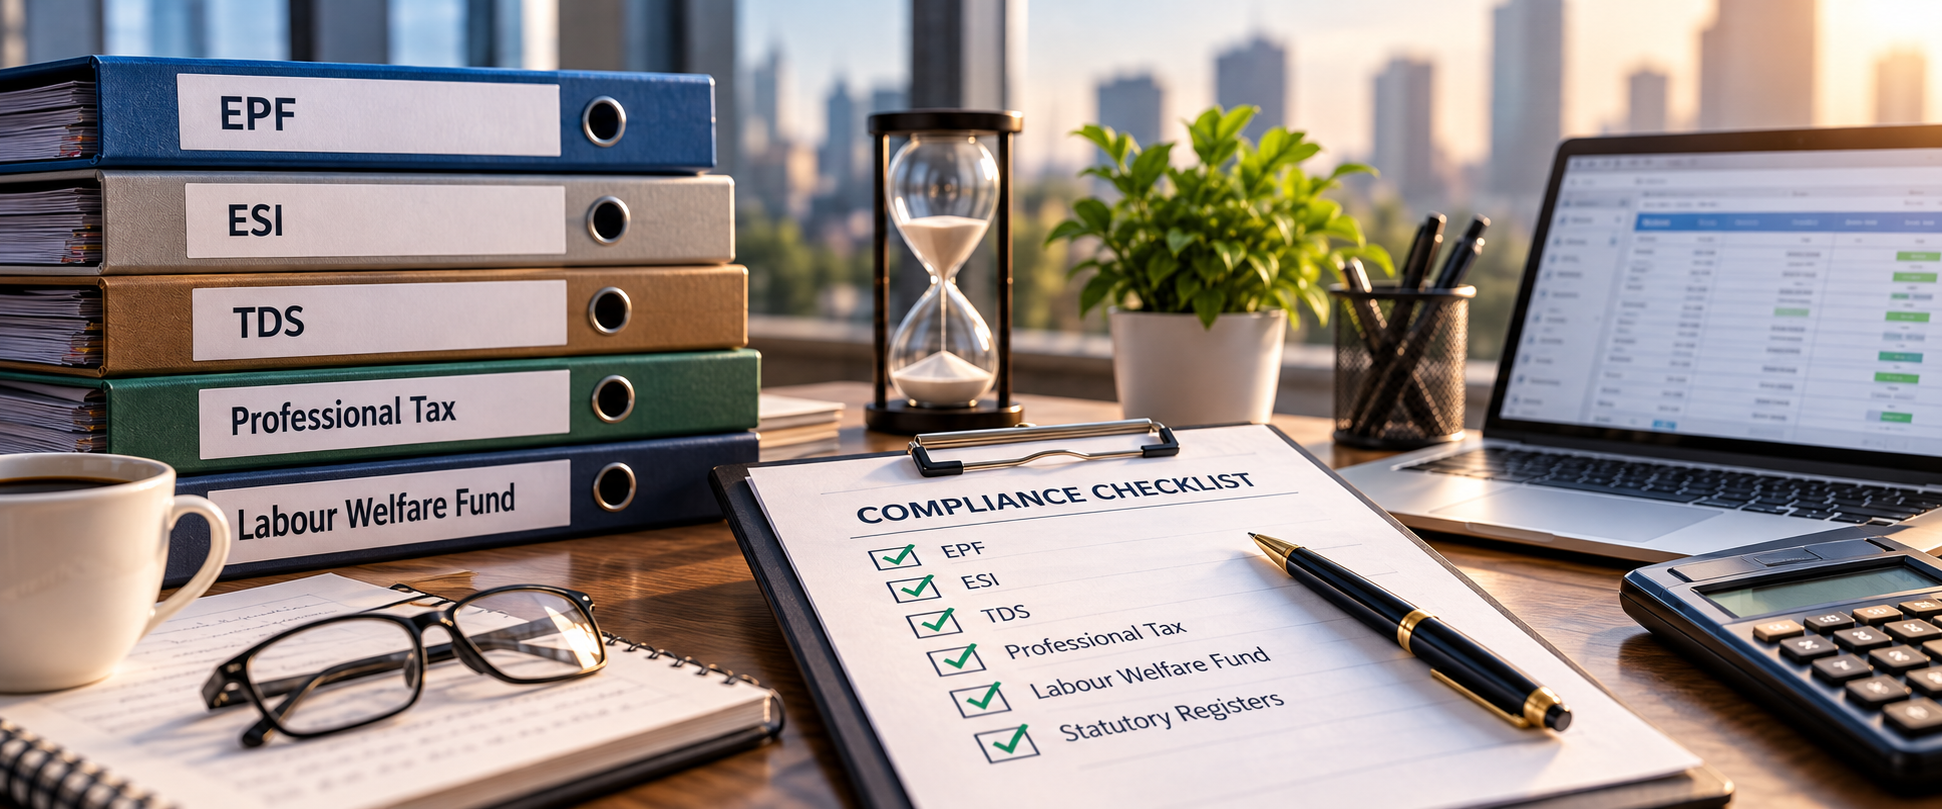
1. Provident Fund (EPF)

Applies to: Establishments with 20 or more employees. Voluntary registration is available below that threshold.

What is required:

Register the establishment and obtain an EPF code. Deduct the employee contribution and add the employer contribution each month. File the monthly ECR (Electronic Challan cum Return) and deposit the challan.

Deadline: 15th of the following month.

Where businesses slip: Treating contract workers and consultants inconsistently. Misclassifying an employee as a consultant to avoid the contribution is a common shortcut that creates significant liability during an inspection.

2. Employees’ State Insurance (ESI)

Applies to: Establishments with 10 or more employees (20 in some states), covering employees earning up to the prescribed wage ceiling.

What is required:

Obtain an ESI code for the establishment. Register each eligible employee and generate their insurance number. Deduct and deposit monthly contributions.

Deadline: 15th of the following month. Half-yearly returns are filed in May and November.

Where businesses slip: Failing to re-assess coverage when an employee’s wages cross or fall below the ceiling mid-year. Coverage is determined at the start of each contribution period, not continuously.

3. Tax Deducted at Source (TDS) on Salaries

Applies to: Every employer paying taxable salary.

What is required:

Calculate TDS based on each employee’s declared investments and chosen tax regime. Deposit the deducted amount monthly. File quarterly TDS returns in Form 24Q. Issue Form 16 to employees annually.

Deadlines: TDS deposit by the 7th of the following month. Quarterly returns by the 31st of the month following each quarter, with the Q4 return due 31st May. Form 16 issued by 15th June.

Where businesses slip: Accepting investment declarations in April and never collecting proof in January. When employees fail to produce documentation, the shortfall becomes the employer’s problem in the fourth quarter.

4. Professional Tax

Applies to: Businesses operating in states that levy it, including Maharashtra, Karnataka, West Bengal, Tamil Nadu, Gujarat and others. Delhi does not currently levy professional tax.

What is required:

Registration certificate for the employer and enrolment certificate for employees. Deduction at state-specified slab rates and periodic filing.

Deadline: Varies by state, monthly in some, annually in others.

Where businesses slip: Multi-state operations. A company headquartered in Delhi with a sales team in Mumbai still has a Maharashtra professional tax obligation, and it is routinely overlooked.

5. Labour Welfare Fund

Applies to: Establishments in states that operate a welfare fund, including Maharashtra, Karnataka, Haryana and others.

What is required:

Employee and employer contributions at state-specified rates, deposited on the state’s schedule, typically half-yearly or annually.

6. Statutory Registers and Records

Beyond the filings, several registers must be maintained and produced on demand during an inspection: the register of wages, register of employees, attendance records, leave register, and records under the Payment of Bonus Act and Payment of Gratuity Act where applicable.

These are the records that get requested first during any labour inspection, and incomplete registers often cause more difficulty than a late filing would have.

The Annual Obligations Businesses Forget

Monthly filings get attention because they recur. Annual obligations get missed because they arrive once and there is no routine built around them.

Bonus payment under the Payment of Bonus Act must be paid within eight months of the close of the accounting year, with Form D filed accordingly.

Gratuity provisioning applies to employees completing five years of continuous service, and the liability should be recognised in your books rather than discovered at the point of exit.

Annual returns under applicable Shops and Establishments Acts vary by state and are commonly overlooked by businesses that registered years ago and never revisited the requirement.

Form 16 issuance to every employee from whom TDS was deducted, including those who left during the year.

Building Controls Instead of Relying on Memory

A checklist only works if something enforces it. The organisations that stay compliant do not have better memories, they have better controls.

That means documented approval workflows before disbursement, segregation between the person who prepares payroll and the person who approves it, a reconciliation between the payroll register and the bank disbursement every month, and an audit trail for every change to employee master data.

This is the thinking behind internal controls in payroll systems, and it is also why many businesses move to paperless payroll processing, a digital trail is far easier to audit than a folder of signed printouts.

For organisations that want an independent assessment of where the gaps actually are, a regulatory compliance audit will identify exposure before a regulator does.

When Outsourcing Makes More Sense Than Hiring

There is a point at which building payroll capability in-house stops being economical.

A compliance-capable payroll resource needs to track amendments across multiple statutes, manage state-wise variation, and stay current with filing portals that change without notice. For a company with under two hundred employees, that is rarely a full role, but the knowledge requirement is the same as it would be for a company with two thousand.

Outsourcing resolves the mismatch. You get the specialist knowledge without carrying the headcount, and the liability for accuracy sits with a provider whose entire business depends on getting it right.

ACATL provides payroll outsourcing for corporate organisations covering the complete cycle, processing, statutory challans, return filing, and ESI, EPF and EPT code management. For businesses rethinking their pay structures alongside the move, our compensation consulting work addresses structure and tax efficiency together.

Many clients combine payroll with accounting outsourcing so that payroll entries flow directly into the books without a reconciliation step, and with assurance and attestation where statutory certification is required.

A Note for Early-Stage Companies

Newly incorporated companies face the same obligations as established ones, usually without anyone internally responsible for tracking them.

The first year typically requires statutory auditor appointment within thirty days of incorporation, board meetings with maintained registers, GST registration where applicable, and PF and ESI registration triggered the moment headcount crosses the threshold.

Founders also benefit from addressing documentation early founders’ agreements, employment contracts and vendor agreements. Our legal assistance team handles this alongside the compliance work, and protecting the business identity through trademark registration is considerably cheaper at this stage than resolving a dispute later.

Where to Start

If you are unsure where your organisation currently stands, start with three questions. Are all applicable registrations in place for every state you operate in? Has every monthly filing for the current financial year been deposited on time? Are your statutory registers complete and available if an inspector asked tomorrow?

If any answer is uncertain, that is the gap worth closing first.

ACATL has supported businesses across Delhi NCR for over twenty-three years with payroll, compliance and corporate services. Get in touch for a review of your current payroll compliance position we will tell you exactly what needs attention and in what order.
Why You Need a Regulatory Compliance Audit for Your Business

Every business owner focuses on increasing sales, improving customer satisfaction, and expanding operations. However, many overlook one critical factor that directly impacts long-term business success, regulatory compliance. A company may be profitable, have loyal customers, and enjoy strong market demand, but if it fails to comply with applicable laws and regulations, even a minor compliance lapse can lead to financial penalties, legal notices, reputational damage, or operational disruptions.

One of the most effective ways to avoid these risks is by conducting a regulatory compliance audit. Rather than waiting for government authorities to identify mistakes, businesses can proactively review their compliance status, identify gaps, and implement corrective measures before they become costly issues.

Today, organizations across India are increasingly adopting regulatory compliance audit India services not just to meet legal obligations but also to strengthen governance, improve operational efficiency, and build trust with investors, lenders, customers, and regulatory authorities.

What Is a Regulatory Compliance Audit?

A regulatory compliance audit is a systematic review of a company’s legal, financial, operational, and statutory obligations to ensure it complies with applicable laws, industry regulations, and government requirements.

Unlike a financial audit, which primarily verifies financial statements, a compliance audit evaluates whether a business is meeting its statutory responsibilities. This includes reviewing corporate filings, GST compliance, payroll records, labour law obligations, tax filings, accounting practices, licenses, internal policies, and governance processes.

Professional corporate compliance services India conduct these audits by examining documentation, verifying filings, assessing internal controls, and identifying areas where corrective action is required.

The objective is not simply to identify mistakes but to help businesses establish sustainable compliance systems.

Compliance Risks Often Remain Hidden Until It’s Too Late

Many businesses assume they are fully compliant simply because they have never received a government notice. Unfortunately, regulatory risks often remain unnoticed for months or even years until an inspection, investor due diligence, or statutory audit exposes them.

Common compliance issues include delayed ROC filings, incorrect GST returns, missing employee documentation, payroll calculation errors, outdated statutory registers, expired licenses, inaccurate tax deductions, and undocumented board resolutions.

These problems rarely appear overnight. They usually develop gradually through small administrative oversights that accumulate over time.

Regular business compliance solutions India help organizations identify these hidden risks before they result in penalties or legal complications.

Regulatory Audits Protect Businesses from Financial Penalties

One of the primary reasons businesses conduct compliance audits is to avoid unnecessary financial losses.

Late statutory filings, incorrect tax reporting, payroll non-compliance, labour law violations, and incomplete documentation may attract penalties, additional filing fees, interest charges, or legal proceedings.

These expenses often exceed the cost of maintaining proper compliance systems.

By conducting periodic regulatory compliance audit India, businesses gain sufficient time to correct deficiencies before government authorities identify them.

Preventive compliance is always more cost-effective than corrective compliance.

Strong Compliance Builds Investor Confidence

Modern investors evaluate businesses far beyond their revenue and profitability.

During due diligence, they carefully review statutory filings, taxation records, accounting systems, employment compliance, governance practices, legal agreements, intellectual property, and regulatory history.

Compliance gaps increase perceived investment risk because they suggest weak internal controls or poor operational discipline.

Organizations maintaining regular Governance Risk and Compliance India practices demonstrate greater transparency, accountability, and business maturity.

This significantly improves investor confidence while supporting successful fundraising and business expansion.

Enterprise Customers Prefer Compliance-Ready Vendors

Large organizations increasingly perform vendor due diligence before awarding contracts.

Corporate procurement teams often verify GST registrations, statutory compliance, financial reporting, labour law compliance, certifications, and legal documentation before approving suppliers.

Businesses with organized compliance records complete vendor onboarding more quickly and establish stronger commercial relationships.

Professional legal compliance services India help companies maintain accurate documentation that satisfies enterprise procurement requirements while reducing delays in business development.

Compliance therefore contributes directly to revenue opportunities.

Payroll Compliance Requires Continuous Monitoring

Payroll is one of the most sensitive compliance areas because it directly affects both employees and statutory authorities.

Businesses must ensure accurate salary calculations, tax deductions, Provident Fund contributions, Employee State Insurance compliance, leave management, reimbursements, bonus payments, and statutory reporting.

Manual payroll processes often create avoidable errors that affect employee trust and regulatory compliance.

Professional payroll outsourcing services India simplify payroll administration while ensuring statutory obligations remain fully compliant throughout the year.

Payroll audits also help organizations identify inconsistencies before they impact employee satisfaction or government inspections.

Financial Accuracy Supports Better Compliance

Accounting and compliance are closely connected.

Accurate books of accounts provide the foundation for taxation, statutory filings, audits, financial reporting, and regulatory documentation.

If accounting records contain inconsistencies, compliance problems usually follow.

Professional accounting outsourcing services India help businesses maintain updated financial records, reconcile transactions, prepare statutory reports, and support regulatory audits.

Reliable accounting systems reduce compliance risks while improving business decision-making.

Compliance Audits Improve Internal Governance

Many organizations associate compliance only with government regulations. However, internal governance is equally important.

Compliance audits evaluate whether management approvals are documented, board meetings are conducted properly, statutory registers are maintained, company policies are followed, and internal responsibilities remain clearly defined.

Strong governance reduces operational confusion while improving accountability across departments.

Businesses implementing Governance Risk and Compliance India frameworks often experience smoother operations because employees understand their responsibilities and organizational processes become standardized.

Regulatory Changes Require Continuous Review

India’s regulatory environment evolves regularly.

Tax regulations, labour laws, corporate filing requirements, digital reporting standards, and compliance procedures continue changing as government authorities modernize regulatory systems.

Businesses relying on outdated compliance practices risk unintentionally violating new regulations.

Periodic compliance audits ensure internal systems remain aligned with current legal requirements.

Organizations working with experienced compliance professionals receive timely guidance regarding regulatory changes and their business implications.

Compliance Audits Strengthen Business Reputation

Reputation has become one of the most valuable business assets.

Customers trust compliant organizations.

Banks prefer lending to compliant businesses.

Investors favour transparent companies.

Enterprise clients select reliable vendors.

Government authorities interact more efficiently with professionally managed organizations.

A strong compliance record demonstrates operational discipline, ethical business practices, and responsible leadership.

These qualities strengthen credibility across every stakeholder group.

Technology Makes Compliance Audits More Efficient

Digital transformation has significantly improved compliance management.

Cloud accounting platforms, automated payroll systems, digital document management, compliance dashboards, workflow automation, and reporting tools allow businesses to monitor regulatory obligations more efficiently.

Technology reduces administrative effort while improving reporting accuracy.

However, successful compliance still depends on professional expertise capable of interpreting regulations, identifying risks, and recommending practical corrective actions.

The combination of technology and experienced advisors produces the strongest compliance outcomes.

Why Every Growing Business Should Schedule Regular Compliance Audits

Many organizations conduct compliance reviews only after receiving notices or preparing for investment.

This reactive approach increases business risk.

Instead, businesses should perform periodic compliance audits regardless of company size.

Regular reviews create opportunities to improve documentation, strengthen governance, correct filing errors, update statutory records, improve payroll processes, and maintain financial accuracy before issues become significant.

Compliance should become a continuous management practice rather than an occasional administrative activity.

Conclusion

A regulatory compliance audit is far more than a legal formality. It is a strategic business exercise that protects organizations from financial penalties, operational disruptions, legal disputes, and reputational damage while strengthening governance and investor confidence.

Businesses investing in regulatory compliance audit India, corporate compliance services India, business compliance solutions India, legal compliance services India, accounting outsourcing services India, payroll outsourcing services India, and Governance Risk and Compliance India build stronger operational foundations capable of supporting sustainable growth.

In today’s increasingly regulated business environment, organizations that review their compliance regularly are not simply avoiding risks, they are creating businesses that are more trustworthy, investment-ready, and prepared for long-term success.