Business Compliance in India: What Companies Actually Need at Every Stage

Nobody starts a business to manage compliance. You start it to build something, sell something, solve a problem for someone. The filings and registrations are the part you deal with because you have to.

The difficulty is that compliance obligations in India do not arrive all at once. They accumulate. A requirement triggers when your headcount crosses ten. Another when turnover crosses a threshold. A third when you open an office in a second state. Each one arrives quietly, and the only notification you receive is usually a penalty notice eighteen months later.

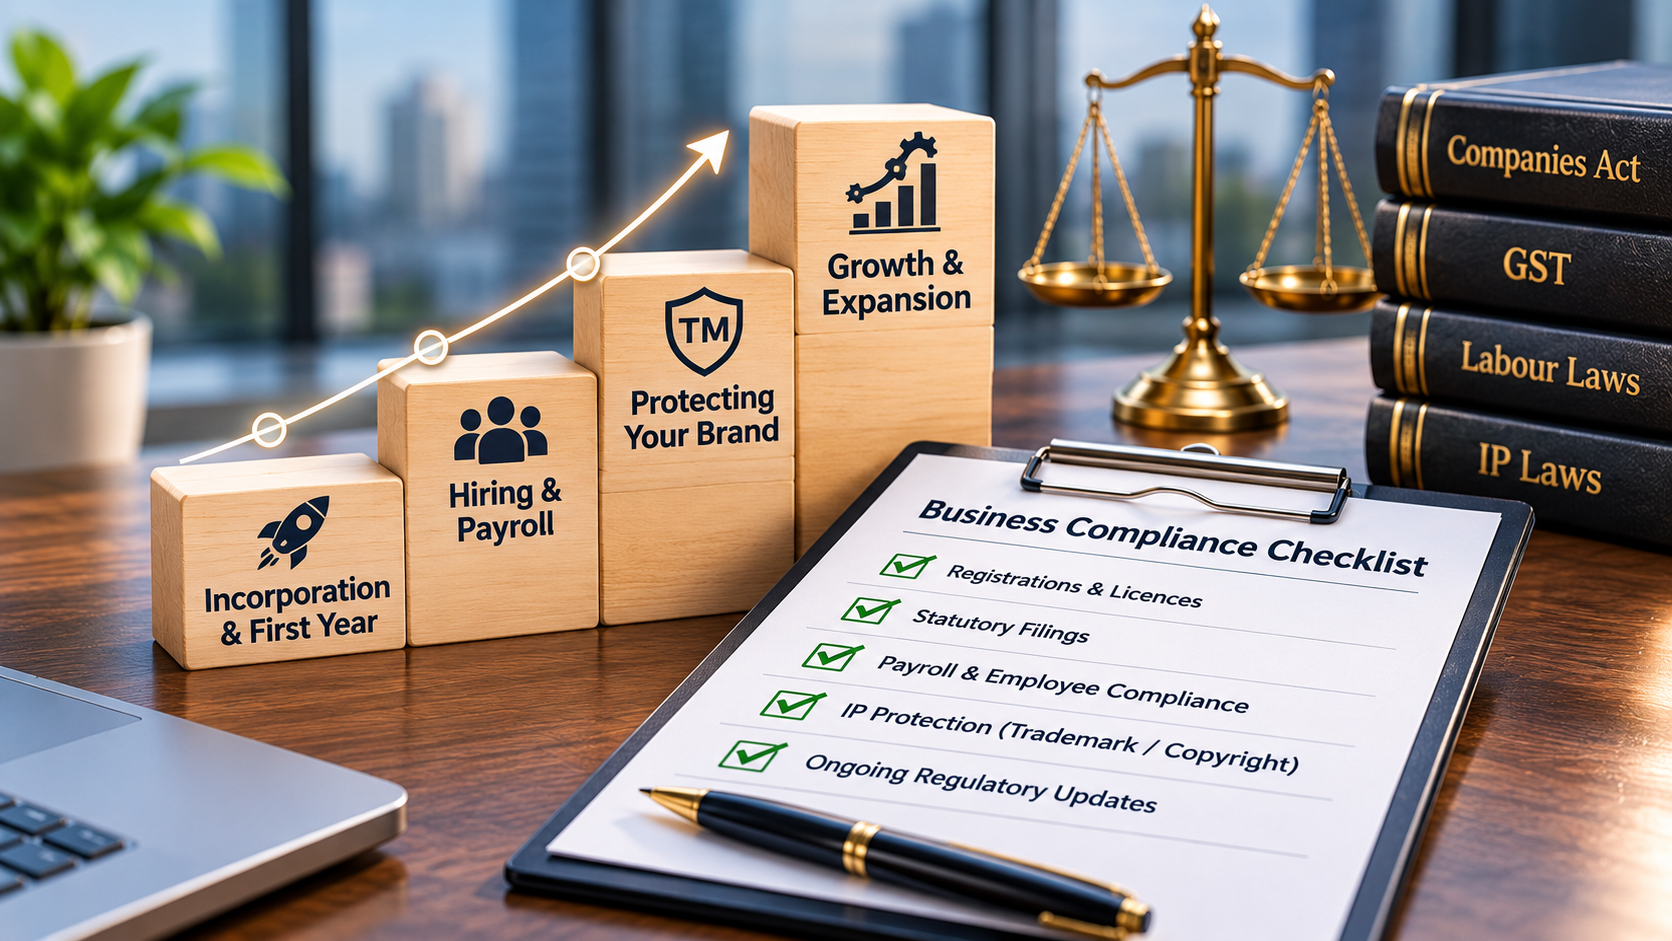
This guide maps what applies at each stage of a business, so you can see what is coming before it becomes a problem.

Stage One: The First Year After Incorporation

The first twelve months carry more compliance weight than most founders expect, and almost none of it is intuitive.

Within the first thirty days

A statutory auditor must be appointed. This is not optional and not deferrable. The board appoints the first auditor within thirty days of incorporation, and if the board fails to do so, the members must appoint one within ninety days.

Within the first six months

The company must hold its first board meeting within thirty days of incorporation, and maintain minutes of it. The commencement of business declaration must be filed. Statutory registers need to be opened and maintained, including the register of members, register of directors and register of charges.

Registrations that trigger on activity

GST registration becomes mandatory once turnover crosses the threshold, or immediately if you are making inter state supplies. Provident fund registration triggers at twenty employees, employees’ state insurance at ten in most states. Professional tax registration applies in states that levy it, and this catches companies with remote employees in other states more often than anything else.

Annual filings

AOC-4 for financial statements, MGT-7 for the annual return, and DIR-3 KYC for every director. These are the filings that generate the most penalty notices simply because new companies do not realise they apply from year one regardless of revenue.

Our regulatory compliance audit and management services exist largely because this stage goes wrong so often, and because fixing it retroactively costs several times more than doing it correctly.

Stage Two: When You Start Hiring

The moment you have employees, payroll becomes a monthly legal obligation rather than a finance task.

You are now managing provident fund contributions with ECR filing by the fifteenth of each month, employees’ state insurance with its own monthly deposit and half yearly returns, TDS on salaries with monthly deposits and quarterly returns in Form 24Q, professional tax wherever applicable, and labour welfare fund contributions in states that operate one.

Alongside the filings sit the registers. Register of wages, attendance records, leave register, and records under the Payment of Bonus Act and Payment of Gratuity Act. These are the first things an inspector asks for, and incomplete registers cause more difficulty than a late filing usually does.

Most companies reach a point where this stops being worth doing internally. The knowledge required spans multiple statutes and changes constantly, but the volume rarely justifies a dedicated hire. That mismatch is the entire argument for payroll outsourcing, and it is why companies with forty employees and companies with four hundred often arrive at the same conclusion.

Stage Three: When Your Brand Becomes Worth Protecting

Intellectual property is the most commonly deferred item on any compliance list, and the deferral is usually discovered at the worst possible moment.

The pattern is predictable. A business operates for three or four years, builds genuine recognition under its name, and then either receives a cease and desist from someone who registered a similar mark, or discovers during due diligence that it owns nothing it thought it owned.

Your brand name and logo fall under trademark law. Registration gives you exclusive rights across India in the classes you register, and the priority date is the date you file, not the date you started using it. This is why filing early matters even though registration takes twelve to eighteen months. Trademark registration is the single highest value IP step for most businesses.

Original creative work including written content, software code, designs, photography and audio falls under copyright. Protection exists automatically from creation, but proving ownership in a dispute requires documentation that most businesses cannot produce. Copyright registration provides exactly that proof.

The visual appearance of a product is protected separately through design registration, which covers shape, configuration, pattern and ornamentation rather than function.

A functional invention requires patent registration, which is a longer and more technical process but the only route to protecting how something actually works.

An audio identifier, a jingle or signature sound associated with your brand, can be protected through sound mark registration.

Products tied to a geographical origin may qualify for protection under geographical indications, which matters significantly for businesses in traditional manufacturing, textiles, handicrafts and agricultural products.

Most growing businesses need two or three of these. Very few have any of them.

Stage Four: When Books and Reporting Become Serious

In the early years, accounting is often whatever the founder or an external accountant manages between other priorities. That stops working at a certain point.

The transition usually happens when one of three things occurs. An investor or lender asks for financials that must stand up to scrutiny. The volume of transactions exceeds what ad hoc bookkeeping can handle accurately. Or a statutory audit threshold is crossed and the books must be audit ready rather than merely complete.

This is where accounting outsourcing tends to make more sense than building an internal finance function, particularly for businesses between twenty and two hundred employees where the workload is real but not enough to justify a full team.

Where independent verification is required, whether for lenders, investors, regulators or clients, assurance and attestation provides the certification that carries weight with third parties.

Stage Five: When Contracts Start Costing You

Businesses operate on documentation long before they recognise it as documentation.

A co founder relationship with no founders’ agreement. Employees working under offer letters that contain none of the protections an employment contract would. Vendors engaged over email with no written terms. Clients served without a service agreement defining scope, payment terms or liability.

None of this causes a problem until it does. And when it does, the absence of a document is what determines the outcome, not the fairness of your position.

The documents most businesses need and most businesses lack are founders’ agreements, employment contracts with confidentiality and IP assignment clauses, non disclosure agreements, vendor and client service agreements, and terms and privacy policy for any website or application.

Our legal assistance team handles drafting and review of exactly these, and the work is considerably cheaper before a dispute than during one.

The Mistakes That Cost the Most

Across twenty three years of working with businesses in Delhi NCR and beyond, certain errors repeat.

Treating compliance as annual rather than continuous. Most obligations are monthly or quarterly. A business that thinks about compliance once a year is already behind on most of them.

Missing multi state obligations. A company registered in Delhi with three employees in Bangalore has Karnataka professional tax obligations and possibly state specific labour registrations. This is the single most commonly missed category.

Not noticing threshold triggers. Headcount crossing ten or twenty, turnover crossing a GST or audit threshold. Nobody is watching, so the requirement activates silently and the breach accumulates.

Misclassifying employees as consultants. This is done to avoid PF and ESI contributions and it is identified routinely during inspections. The liability includes arrears, interest and penalty.

Deferring IP until there is a problem. By the time there is a problem, your options are expensive and your position is weak.

Maintaining registers retroactively. Reconstructed records are usually identifiable and create a credibility issue broader than the original gap.

How to Know Where You Stand

Three questions give you most of the picture.

Do you have a written list of every compliance obligation that applies to your business across every state you operate in? Most companies have never created one, which means nobody can confirm whether anything is missing.

Can you produce acknowledgements for every statutory filing from the last two financial years? If this requires a search rather than a lookup, your record keeping has a gap.

If an inspector requested your statutory registers tomorrow, would they be complete and contemporaneous? Not reconstructable, but complete.

Uncertainty in any of these is worth resolving before someone external identifies it for you.

Where ACATL Fits

ACATL has supported businesses across Delhi NCR and India for over twenty three years, with more than a thousand clients across manufacturing, healthcare, education, real estate, food and beverage, logistics, retail and professional services.

The work covers the full range a growing business needs. Regulatory compliance audit and management. Payroll outsourcing. Accounting outsourcing. Assurance and attestation. Legal assistance. And the complete spectrum of intellectual property registration.

The advantage of handling these together is that they are genuinely interconnected. Payroll generates statutory obligations. Those obligations are what a compliance audit examines. The contracts your legal team drafts determine what your accounting function records. Treating them as separate vendors creates gaps at exactly the points where they overlap.

If you are unsure where your business currently stands, contact our team for an assessment. We will tell you what applies, what is missing, and what to address first.

You can also follow our legal updates for amendments that affect Indian businesses, and see who we work with across industries.
Why You Need a Regulatory Compliance Audit for Your Business

Every business owner focuses on increasing sales, improving customer satisfaction, and expanding operations. However, many overlook one critical factor that directly impacts long-term business success, regulatory compliance. A company may be profitable, have loyal customers, and enjoy strong market demand, but if it fails to comply with applicable laws and regulations, even a minor compliance lapse can lead to financial penalties, legal notices, reputational damage, or operational disruptions.

One of the most effective ways to avoid these risks is by conducting a regulatory compliance audit. Rather than waiting for government authorities to identify mistakes, businesses can proactively review their compliance status, identify gaps, and implement corrective measures before they become costly issues.

Today, organizations across India are increasingly adopting regulatory compliance audit India services not just to meet legal obligations but also to strengthen governance, improve operational efficiency, and build trust with investors, lenders, customers, and regulatory authorities.

What Is a Regulatory Compliance Audit?

A regulatory compliance audit is a systematic review of a company’s legal, financial, operational, and statutory obligations to ensure it complies with applicable laws, industry regulations, and government requirements.

Unlike a financial audit, which primarily verifies financial statements, a compliance audit evaluates whether a business is meeting its statutory responsibilities. This includes reviewing corporate filings, GST compliance, payroll records, labour law obligations, tax filings, accounting practices, licenses, internal policies, and governance processes.

Professional corporate compliance services India conduct these audits by examining documentation, verifying filings, assessing internal controls, and identifying areas where corrective action is required.

The objective is not simply to identify mistakes but to help businesses establish sustainable compliance systems.

Compliance Risks Often Remain Hidden Until It’s Too Late

Many businesses assume they are fully compliant simply because they have never received a government notice. Unfortunately, regulatory risks often remain unnoticed for months or even years until an inspection, investor due diligence, or statutory audit exposes them.

Common compliance issues include delayed ROC filings, incorrect GST returns, missing employee documentation, payroll calculation errors, outdated statutory registers, expired licenses, inaccurate tax deductions, and undocumented board resolutions.

These problems rarely appear overnight. They usually develop gradually through small administrative oversights that accumulate over time.

Regular business compliance solutions India help organizations identify these hidden risks before they result in penalties or legal complications.

Regulatory Audits Protect Businesses from Financial Penalties

One of the primary reasons businesses conduct compliance audits is to avoid unnecessary financial losses.

Late statutory filings, incorrect tax reporting, payroll non-compliance, labour law violations, and incomplete documentation may attract penalties, additional filing fees, interest charges, or legal proceedings.

These expenses often exceed the cost of maintaining proper compliance systems.

By conducting periodic regulatory compliance audit India, businesses gain sufficient time to correct deficiencies before government authorities identify them.

Preventive compliance is always more cost-effective than corrective compliance.

Strong Compliance Builds Investor Confidence

Modern investors evaluate businesses far beyond their revenue and profitability.

During due diligence, they carefully review statutory filings, taxation records, accounting systems, employment compliance, governance practices, legal agreements, intellectual property, and regulatory history.

Compliance gaps increase perceived investment risk because they suggest weak internal controls or poor operational discipline.

Organizations maintaining regular Governance Risk and Compliance India practices demonstrate greater transparency, accountability, and business maturity.

This significantly improves investor confidence while supporting successful fundraising and business expansion.

Enterprise Customers Prefer Compliance-Ready Vendors

Large organizations increasingly perform vendor due diligence before awarding contracts.

Corporate procurement teams often verify GST registrations, statutory compliance, financial reporting, labour law compliance, certifications, and legal documentation before approving suppliers.

Businesses with organized compliance records complete vendor onboarding more quickly and establish stronger commercial relationships.

Professional legal compliance services India help companies maintain accurate documentation that satisfies enterprise procurement requirements while reducing delays in business development.

Compliance therefore contributes directly to revenue opportunities.

Payroll Compliance Requires Continuous Monitoring

Payroll is one of the most sensitive compliance areas because it directly affects both employees and statutory authorities.

Businesses must ensure accurate salary calculations, tax deductions, Provident Fund contributions, Employee State Insurance compliance, leave management, reimbursements, bonus payments, and statutory reporting.

Manual payroll processes often create avoidable errors that affect employee trust and regulatory compliance.

Professional payroll outsourcing services India simplify payroll administration while ensuring statutory obligations remain fully compliant throughout the year.

Payroll audits also help organizations identify inconsistencies before they impact employee satisfaction or government inspections.

Financial Accuracy Supports Better Compliance

Accounting and compliance are closely connected.

Accurate books of accounts provide the foundation for taxation, statutory filings, audits, financial reporting, and regulatory documentation.

If accounting records contain inconsistencies, compliance problems usually follow.

Professional accounting outsourcing services India help businesses maintain updated financial records, reconcile transactions, prepare statutory reports, and support regulatory audits.

Reliable accounting systems reduce compliance risks while improving business decision-making.

Compliance Audits Improve Internal Governance

Many organizations associate compliance only with government regulations. However, internal governance is equally important.

Compliance audits evaluate whether management approvals are documented, board meetings are conducted properly, statutory registers are maintained, company policies are followed, and internal responsibilities remain clearly defined.

Strong governance reduces operational confusion while improving accountability across departments.

Businesses implementing Governance Risk and Compliance India frameworks often experience smoother operations because employees understand their responsibilities and organizational processes become standardized.

Regulatory Changes Require Continuous Review

India’s regulatory environment evolves regularly.

Tax regulations, labour laws, corporate filing requirements, digital reporting standards, and compliance procedures continue changing as government authorities modernize regulatory systems.

Businesses relying on outdated compliance practices risk unintentionally violating new regulations.

Periodic compliance audits ensure internal systems remain aligned with current legal requirements.

Organizations working with experienced compliance professionals receive timely guidance regarding regulatory changes and their business implications.

Compliance Audits Strengthen Business Reputation

Reputation has become one of the most valuable business assets.

Customers trust compliant organizations.

Banks prefer lending to compliant businesses.

Investors favour transparent companies.

Enterprise clients select reliable vendors.

Government authorities interact more efficiently with professionally managed organizations.

A strong compliance record demonstrates operational discipline, ethical business practices, and responsible leadership.

These qualities strengthen credibility across every stakeholder group.

Technology Makes Compliance Audits More Efficient

Digital transformation has significantly improved compliance management.

Cloud accounting platforms, automated payroll systems, digital document management, compliance dashboards, workflow automation, and reporting tools allow businesses to monitor regulatory obligations more efficiently.

Technology reduces administrative effort while improving reporting accuracy.

However, successful compliance still depends on professional expertise capable of interpreting regulations, identifying risks, and recommending practical corrective actions.

The combination of technology and experienced advisors produces the strongest compliance outcomes.

Why Every Growing Business Should Schedule Regular Compliance Audits

Many organizations conduct compliance reviews only after receiving notices or preparing for investment.

This reactive approach increases business risk.

Instead, businesses should perform periodic compliance audits regardless of company size.

Regular reviews create opportunities to improve documentation, strengthen governance, correct filing errors, update statutory records, improve payroll processes, and maintain financial accuracy before issues become significant.

Compliance should become a continuous management practice rather than an occasional administrative activity.

Conclusion

A regulatory compliance audit is far more than a legal formality. It is a strategic business exercise that protects organizations from financial penalties, operational disruptions, legal disputes, and reputational damage while strengthening governance and investor confidence.

Businesses investing in regulatory compliance audit India, corporate compliance services India, business compliance solutions India, legal compliance services India, accounting outsourcing services India, payroll outsourcing services India, and Governance Risk and Compliance India build stronger operational foundations capable of supporting sustainable growth.

In today’s increasingly regulated business environment, organizations that review their compliance regularly are not simply avoiding risks, they are creating businesses that are more trustworthy, investment-ready, and prepared for long-term success.