
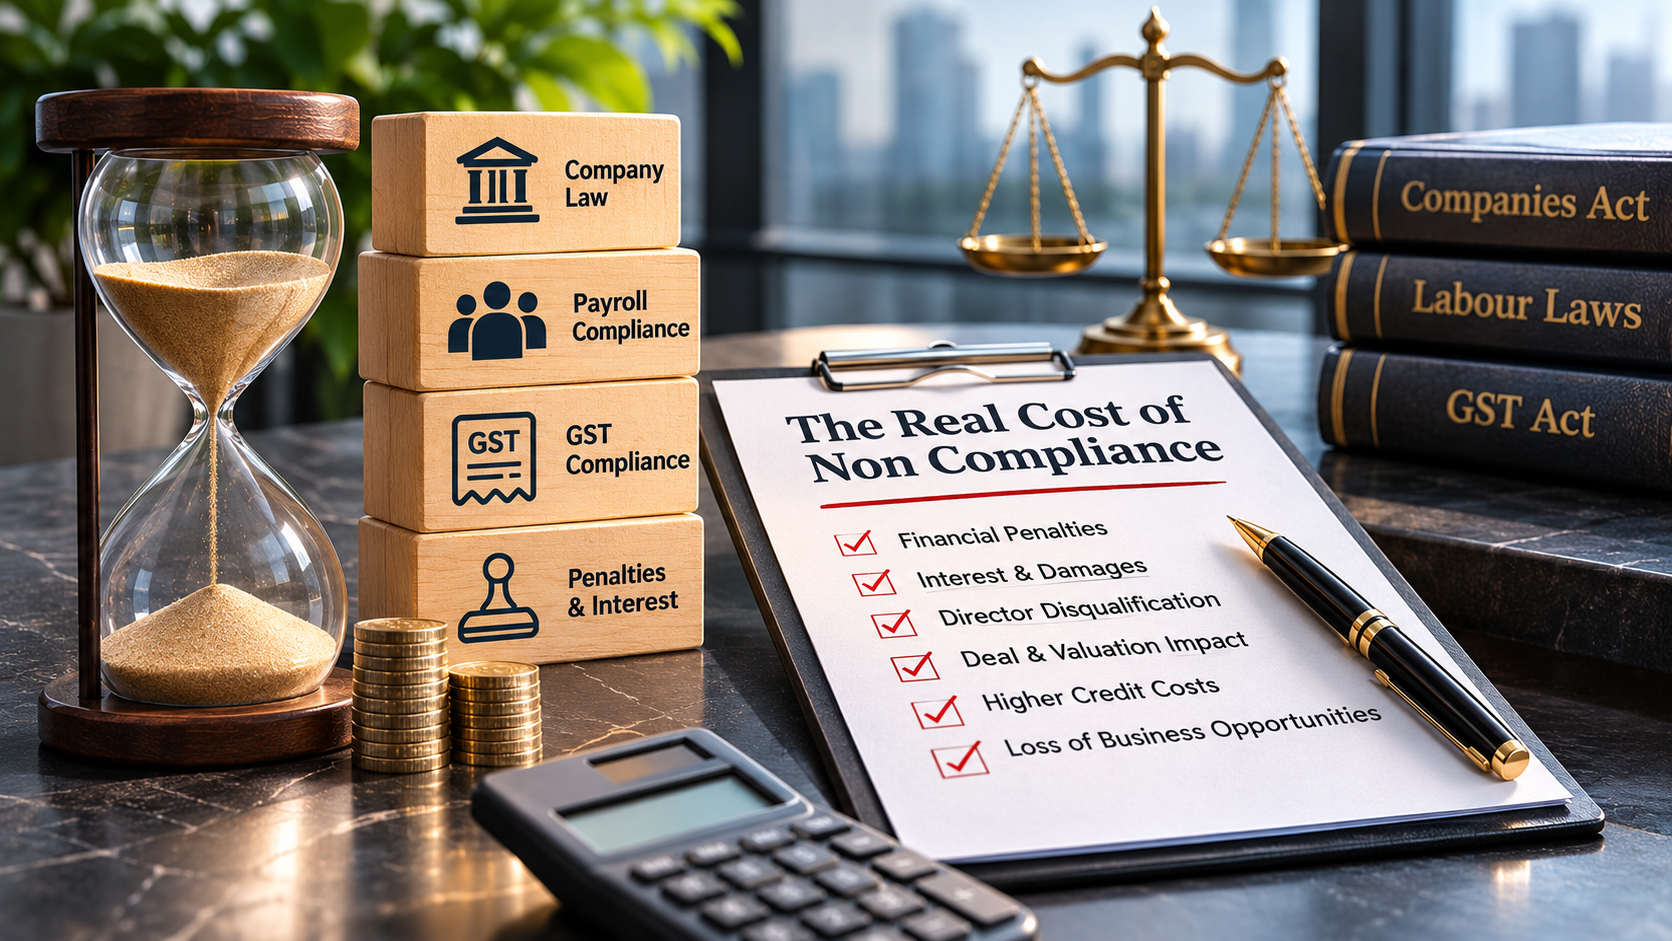
Compliance gets deferred because the cost of ignoring it is invisible, and the cost of addressing it is not.
Hiring help, running an audit, cleaning up registers: all of that has a price tag attached today. Missing a filing has no price tag at all until something forces the issue, which may be years later. So it waits.
The problem with that arithmetic is that it only works if nothing ever surfaces. When something does surface, the bill is rarely a single penalty. It is penalty plus interest plus professional fees plus management time plus whatever opportunity was lost while the matter was being resolved.
Here is what that actually looks like in practice.
Penalties Under the Companies Act
ROC filings are where most companies first discover the cost of delay, because the penalty structure is designed to escalate.
Late filing of annual returns and financial statements attracts an additional fee that accrues per day of delay, with no cap in many cases. A filing that is two years late does not cost twice what a filing one year late costs. It costs considerably more, because the daily accrual continues the entire time.
Failure to appoint a statutory auditor within the prescribed period carries penalties on the company and on every officer in default.
Non maintenance of statutory registers attracts penalties independent of any filing default, and these are assessed on the company and its officers separately.
Director disqualification is the consequence most businesses do not anticipate. A director of a company that fails to file financial statements or annual returns for a continuous period becomes disqualified, and that disqualification follows the individual to every other company where they hold a directorship. One dormant company with neglected filings can disqualify a director from a profitable one.
The pattern worth noting is that company law penalties apply to officers personally, not only to the entity. This is not a corporate liability that stays inside the company.
Penalties Under Payroll Statutes
Payroll obligations carry both interest and damages, which are assessed separately.
Late provident fund deposits attract interest on the delayed amount plus damages calculated on the duration of the delay. Both accrue until payment, and the damages component increases with the length of the default.
Failure to register when thresholds are crossed creates retrospective liability. The contributions were due from the month the threshold was crossed, not from the month you realised and registered. Arrears, interest and damages apply to the entire intervening period.
Employee misclassification is the costliest version of this. Where consultants are found to be employees in substance, contributions become payable retrospectively for the full period, along with interest and damages. Inspections identify this routinely because the indicators are visible in the arrangement itself.
Late TDS deposits attract interest for every month of delay, plus a separate daily late filing fee for the return, plus penalty provisions where the delay is extended. Failure to deduct at all attracts a higher interest rate from the date the deduction was due.
ESI defaults follow a similar structure of interest plus damages, with the added complication that an employee who should have been covered and was not may have incurred medical costs the employer becomes liable for.
Most of this is avoidable with correct processing, which is the practical argument for payroll outsourcing. The provider fee is almost always smaller than the penalty exposure it removes.
Penalties Under GST
GST defaults attract late fees per day of delay for each return, plus interest on tax paid late, and the two accrue independently.
The larger exposure is input tax credit. Where credit is claimed incorrectly or where a supplier has not filed, the credit can be reversed with interest. For businesses operating on thin margins, a credit reversal across several periods can exceed the direct penalty by a wide margin.
Registration defaults carry their own consequences. Operating without registration where it was required attracts penalty calculated on the tax that should have been paid, and the assessment can go back to the date registration became mandatory.
The Costs That Do Not Appear in Any Penalty Schedule
Statutory penalties are the measurable part. They are rarely the largest part.
Deals that do not close. Investor due diligence and acquisition diligence both examine compliance. Findings do not usually kill a transaction outright. They reduce valuation, expand indemnity obligations, or push a portion of consideration into escrow. The cost here is not a fine, it is a worse deal.
Credit access. Lenders examine filing history. A company with irregular ROC filings and payroll defaults is assessed as higher risk, which affects both approval and pricing.
Contracts lost. Large corporates and public sector buyers increasingly require compliance certification from vendors. A business that cannot produce it is excluded from the tender before the commercial discussion begins.
Management time. This is consistently underestimated. Resolving an accumulated compliance backlog occupies senior people for weeks. That time comes directly out of running the business.
Professional fees. Retrospective remediation requires more professional involvement than ongoing compliance does, and specialists engaged under deadline pressure cost more than planned work.
Reputation with your own team. Employees discovering their PF was not deposited, or that Form 16 cannot be issued, creates a trust problem that outlasts the correction.
Why the Gaps Form
In almost every case the cause is structural rather than deliberate.
Nobody owns it. Compliance sits across finance, HR and the founder, which in practice means it sits nowhere. Responsibility is assumed rather than assigned.
Thresholds trigger silently. Headcount crosses ten or twenty. Turnover crosses a GST or audit threshold. Nothing announces this, so the obligation activates and the breach begins accumulating immediately.
Multi state operations. A company in Delhi with employees in Bangalore and Pune has obligations in all three states. This is the single most commonly missed category, and remote working has made it far more common.
Rules change. Wage ceilings are revised, rates are amended, filing portals change requirements. A process built correctly three years ago may be wrong today, and nobody is checking.
Key person departure. The person who knew the process leaves. The knowledge was never documented. Filings continue falling due while the gap is being rediscovered.
A regulatory compliance audit exists to find these before they compound, and the value is almost entirely in the timing.
The Economics of Fixing It Early
A voluntary compliance review identifies gaps while you still control the timeline. You prioritise, remediate in sequence, and spread the cost.
A forced review happens on someone else’s schedule. A regulator has raised a query, an investor is in diligence, or a client has made certification a contractual condition. Everything becomes urgent, specialists are engaged at short notice, and the penalties have already accrued their full duration.
The same work, done voluntarily, costs a fraction of what it costs under pressure. This is not an argument about ethics. It is just what the numbers show.
Building Something That Does Not Fail Again
Fixing the current backlog without changing the structure means the backlog returns.
Assign ownership explicitly. One named person responsible for compliance, with escalation defined. Not a shared assumption.
Build a compliance calendar. Every obligation, every due date, across every state, with reminders before rather than after.
Install controls at source. Approval workflows, segregation of duties, audit trails on master data changes. Internal controls are what prevent errors rather than detect them afterwards.
Review quarterly, not annually. Most obligations are monthly. Annual review means you find problems nine months late.
Watch thresholds deliberately. Headcount and turnover should be checked against regulatory triggers as a routine item.
Track regulatory change. Either internally, or through a provider whose job it is. Our legal updates cover amendments affecting Indian businesses.
Where Specialist Support Pays for Itself
The knowledge required spans company law, labour law, tax law and state specific regulation, and it changes continuously. For most businesses that is not a full internal role, but the knowledge requirement is identical whether you have fifty employees or five hundred.
ACATL provides compliance risk assessment, internal controls evaluation, regulatory applicability analysis and ongoing compliance management. The work frequently connects to adjacent areas, because the root causes usually do. Payroll generates most statutory obligations, which is why payroll outsourcing often resolves the problem at source. Where books and records are the weakness, accounting outsourcing addresses it. Where contracts and documentation are missing, our legal assistance team handles drafting and review. Where independent certification is required, assurance and attestation provides it.
Businesses that get compliance in order often find intellectual property is the remaining gap, since both are deferred for the same reasons. Trademark registration and copyright registration rarely appear on a statutory checklist, but unprotected brand assets become visible at precisely the wrong moment, usually during the same diligence that examines everything else.
The Question Worth Answering
Not whether your business is compliant. Almost everyone assumes it is.
The question is whether you can demonstrate it. Can you produce acknowledgements for every statutory filing from the last two years? Are your registers complete and contemporaneous? Do you have a written list of every obligation that applies across every state you operate in?
If any of that requires checking rather than confirming, that is the gap worth closing while it is still cheap to close.
ACATL has supported businesses across Delhi NCR and India for over twenty three years. Contact our team for an assessment of where your business actually stands.